Start: What the process looks like for you
The moment you tap to apply, the path is simple: submit info, get a decision, see funds. Many riders and drivers in Mexico City and beyond now try didi prestamos for quick access to cash because the app streamlines verification and disbursement. This guide focuses on the user’s view of creditos en linea — how approval turns into usable money, what each step costs you, and what you can control.
Step-by-step: From application to disbursement
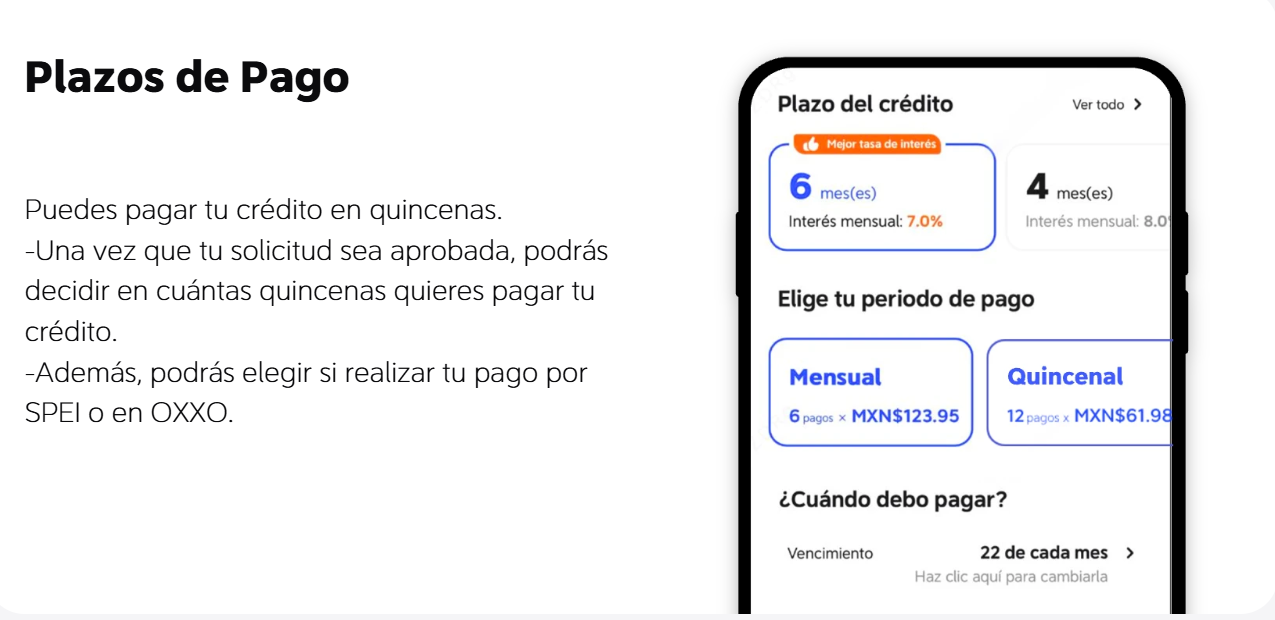
You fill in personal details and income. The app runs a light underwriting check that looks at identity, basic income, and a soft credit score. Approval usually shows within minutes. Then comes the disbursement: money hits your linked bank or e-wallet. The whole flow is designed around speed, but you should read the loan term, APR, and repayment schedule before you accept.
What matters most to users
Interest rate and total cost matter more than a flashy fast approval. A low monthly payment can hide a high APR or long loan term. Watch for origination fees and hidden charges. Keep in mind common industry terms: interest rate, APR, repayment schedule. These affect the real cost of creditos en linea and your monthly budget.
Common mistakes users make — and how to avoid them
People often accept the first offer without comparison. They skip reading the fine print on automatic repayments. They assume approval equals best price — it doesn’t. Always compare offers, check the repayment schedule, and confirm the exact disbursement timeline. Small slip-ups add up fast — and that’s where budgeting matters.
Alternatives to app-only loans
If an app offer feels tight, consider these options: a small bank personal loan, a credit union line, or peer-to-peer lending. Each alternative trades speed for different benefits: banks usually offer lower interest rates; credit unions can be flexible on terms; P2P platforms may have different underwriting. Compare total cost, not just monthly payment.
Real-world anchor: how users in Mexico City experienced app lending
After 2020 more people in urban centers shifted to digital lending for convenience and contact-free service. Drivers in Mexico City reported using apps to bridge short gaps between jobs or repairs. That practical use-case mirrors what many need today: short-term cash that’s reliably disbursed. This is exactly where clear underwriting and transparent fees matter.
What to watch in the app interface
Look for clear sections that show loan amount, APR, fees, and your final repayment schedule. A clean dashboard will show upcoming payments and allow early repayment without penalties. If the app hides fees in multiple screens, that’s a red flag — leave it. Also check whether customer support answers calls or chat quickly — response time matters when money’s involved.
Quick checklist before you tap “Accept”
– Confirm the total amount you will repay, including interest and fees. – Verify the exact disbursement route and time window. – Note the dates and amounts on your repayment schedule. – Check whether early repayment reduces interest. – Keep a copy of the loan contract or a screenshot of final terms.
Final guidance: three golden rules for choosing fast online loans
1) Prioritize total cost over speed — compare APR and fees. 2) Confirm how and when funds are disbursed; timing can affect bills. 3) Keep repayment transparent — choose offers with clear schedules and easy early-pay options.
DiDi Finanzas offers a clear path from approval to cash while keeping those rules front and center — practical, no surprises. —